Yes, a new soft loft can qualify for Ontario’s enhanced HST rebate, which removes up to the full 13% HST, to a maximum of $130,000, on a new home bought as your primary residence. The agreement of purchase and sale must be signed between April 1, 2026 and March 31, 2027, and unlike earlier relief, you don’t have to be a first-time buyer. Hard lofts in converted buildings are almost always resale, so the rebate matters mainly if you’re shopping new or never-occupied loft-style units.
Key takeaways
- The rebate has two parts: up to $80,000 for the 8% provincial portion and up to $50,000 for the 5% federal portion.
- Repeat buyers benefit most, since first-time buyers already had similar relief under $1 million.
- Completed but unsold units can qualify if you sign in the window and are the first to live there.
- The home must be your (or a relation’s) primary residence, not a rental.
- Ask every builder in writing how the rebate is handled in the price.
How the Ontario enhanced HST rebate works
New homes in Ontario carry 13% HST: a 5% federal part and an 8% provincial part. Resale homes generally don’t, which is why this matters only for new construction.
The program announced in the 2026 Ontario Budget has two pieces. According to the CRA’s notice on the enhanced rebate (updated August 2026):
- Ontario enhanced new housing rebate (ENHR): 100% of the 8% provincial HST on homes up to $1 million, to a maximum of $80,000. From $1 million to $1.5 million it’s a flat $80,000. Between $1.5 million and $1.85 million it’s a partial rebate, and at $1.85 million or more only the old Ontario rebate of up to $24,000 applies.
- Ontario new home affordability payment (ONHAP): up to $50,000, covering the 5% federal portion, reduced by any federal rebate you already get. You don’t file a separate application; you consent to share information on your rebate claim.
Combined, that’s the “up to $130,000” you’ve seen in builder ads.
Who qualifies, and does a condo loft count?
The CRA eligibility page lists these conditions for a purchase from a builder:
- You’re an individual buying a new or substantially renovated home, and residential condominium units are expressly included.
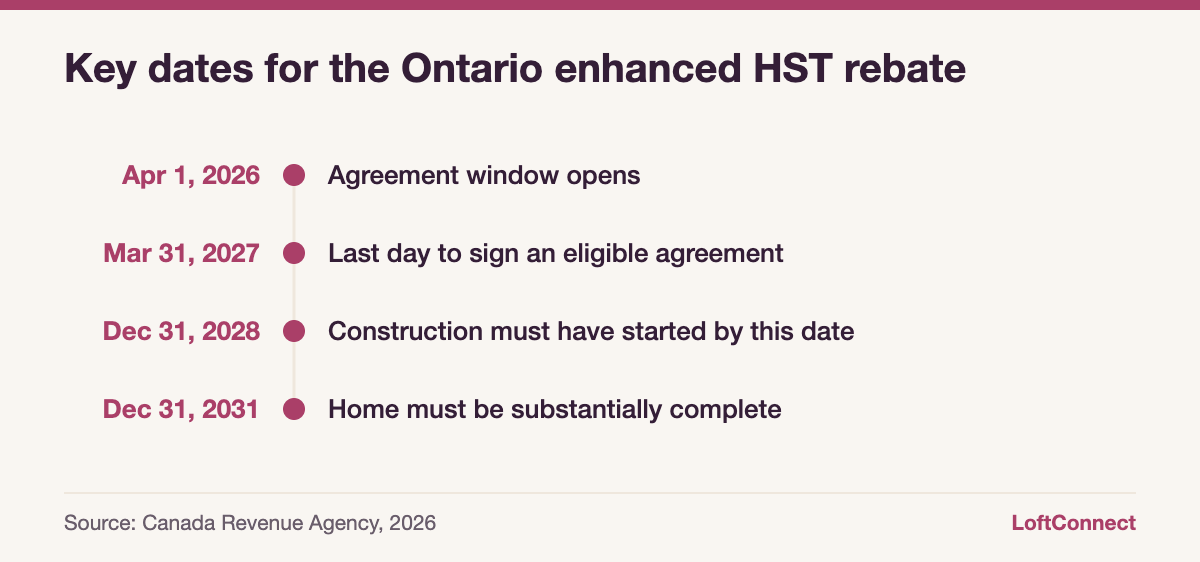
- You signed the agreement on or after April 1, 2026 and on or before March 31, 2027.
- Construction began on or before December 31, 2028, and the home is substantially complete by December 31, 2031.
- The price (before HST) is under $1,850,000.
- The home is for use as your primary residence or a relation’s, and you or that relation are the first to occupy it after it’s complete.
There’s no first-time buyer requirement. The CRA says the home can’t be used as a rental property under this rebate, and a separate notice on an enhanced rental rebate was expected in October 2026. Investors should wait for those rules rather than assume.
Watch the agreement date
If you signed before April 1, 2026, amending your agreement doesn’t make it eligible. A terminated and replaced agreement must have a genuine purpose other than getting the rebate. For assignment sales, both the original agreement and the assignment must fall inside the window, which rules out most older assignments. See our loft assignments page if you’re on either side of one.
What it’s worth: the math at three soft loft prices
For a repeat buyer, the old Ontario new housing rebate topped out at $24,000, and the federal GST new housing rebate disappears above $450,000. So until this year, a repeat buyer of a $900,000 new loft paid almost all of the HST.
| Pre-tax price | 13% HST | ENHR (8% part) | ONHAP (5% part) | Total rebate | HST left to pay |
|---|---|---|---|---|---|
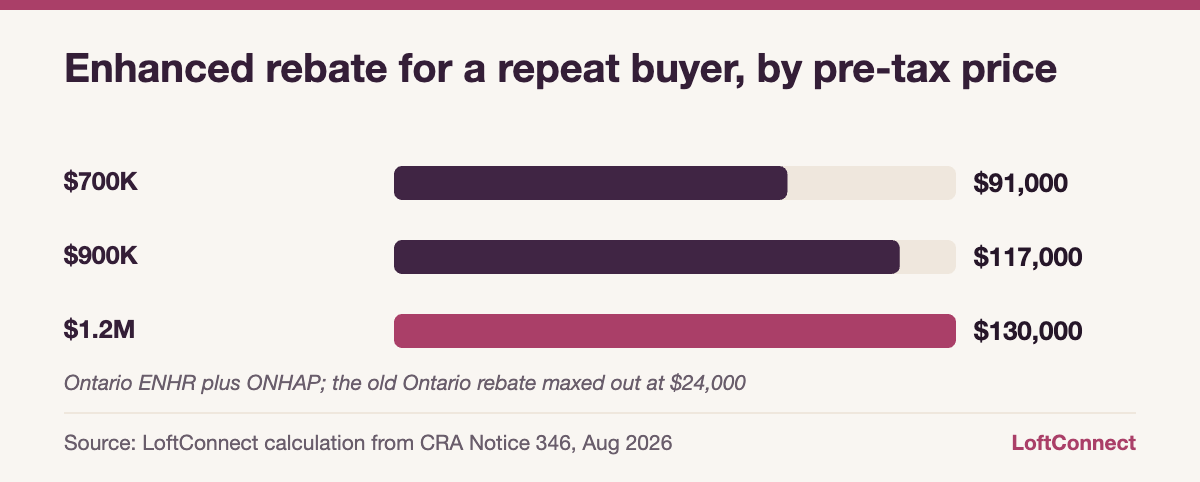
| $700,000 | $91,000 | $56,000 | $35,000 | $91,000 | $0 |
| $900,000 | $117,000 | $72,000 | $45,000 | $117,000 | $0 |
| $1,200,000 | $156,000 | $80,000 | $50,000 | $130,000 | $26,000 |
These assume an eligible repeat buyer with no other federal rebate. At $900,000, the difference between the old $24,000 rebate and the new $117,000 is $93,000.
First-time buyers: less new money, but simpler
If you’re a first-time buyer, you may already qualify for the federal first-time home buyers’ GST/HST rebate (up to $50,000 on homes up to $1 million, phasing out to $1.5 million) and Ontario’s matching first-time relief on the 8% portion. The CRA says you can claim the Ontario first-time rebate and the ENHR together, but the provincial total is capped at $80,000. In practice the enhanced program adds most for first-time buyers between $1 million and $1.5 million, where the federal rebate phases out and the ONHAP can fill the gap.
Why this matters for soft lofts right now
A soft loft is a newer building designed with loft features: tall ceilings, big windows, exposed concrete, open plans. If you’re unsure which you’re looking at, our hard loft vs soft loft explainer covers the differences.
The timing is unusual. Urbanation reported a record 5,001 completed GTHA condo units still held by developers in Q2 2026, up 68% from a year earlier. Those unsold completed units were asking about $1,186 per square foot, compared with roughly $830 for resale units in recently registered projects. Builders sitting on finished inventory have a reason to deal, and the rebate gives buyers extra room.
Because the eligibility rules set a latest construction start date (end of 2028) but no earliest one, a finished unit that nobody has lived in can qualify, provided you sign within the window and are the first occupant. Confirm that with the builder and your lawyer for the specific unit.
How builders apply the rebate in the price
New condo prices in Ontario are usually quoted “HST included,” with the standard rebates assigned to the builder. That convention makes it easy to misread what you’re getting. TRREB’s summary notes you can assign the rebates to the builder and claim through Form GST190 with Schedule RC7190-ON, or pay the full HST at closing and apply to the CRA yourself afterwards.
Ask each builder:
- Is the advertised price before or after the enhanced rebate?
- Will you credit the ENHR and ONHAP at closing, or will I claim them later?
- What happens to my price if the CRA denies the rebate?
- If I’m not eligible (for example, I plan to rent), what is the price?
The CRA warns that if a builder credits a rebate you aren’t entitled to, you and the builder can both be liable to repay it. Don’t sign a primary residence declaration you can’t honour.
Tip: On a soft loft, compare the price per square foot after the rebate with recent resale sales in the same building or a similar one nearby. A $117,000 rebate is meaningful, but if the unit is still priced well above resale, you may be better off in a three-year-old building with the same ceilings and windows.
Protections when you buy new
New condo purchases come with a 10-day cooling-off period under the Condominium Act, during which you can cancel for any reason and get your deposit back. Tarion’s deposit protection on new condos is up to $20,000. The Condo Authority’s buyer guide explains when the cooling-off clock starts. Our pre-construction buying page covers deposits, occupancy fees and closing adjustments.
Frequently asked questions
Does the Ontario HST rebate apply to resale lofts?
No. The enhanced rebate is for new or substantially renovated homes bought from a builder, or homes you build yourself. Resale homes, including almost all hard lofts in converted warehouses, generally don’t charge HST in the first place, so there’s nothing to rebate. The rebate is relevant to new soft lofts and loft-style units in new buildings.
Do I have to be a first-time buyer to get the $130,000 rebate?
No. The enhanced rebate is open to any individual buying an eligible new home as a primary residence for themselves or a relation. First-time buyers can also claim the federal first-time rebate, but total provincial relief is capped at $80,000 and total federal-portion relief at $50,000.
Can I get the rebate on a completed, never-occupied condo?
It appears so, based on the CRA conditions. Construction must have started by December 31, 2028 and be finished by December 31, 2031, with no earliest start date. You must sign between April 1, 2026 and March 31, 2027 and be the first person to live there. Confirm eligibility for the specific unit with your lawyer.
Can I buy a new soft loft as a rental and still get the rebate?
Not under this rebate. The CRA says the home must be your or a relation’s primary residence and cannot be used as a rental property. The CRA said a separate notice on an enhanced rental property rebate would follow in October 2026, so investors should check those rules before signing.
Looking at new soft lofts?
Compare soft lofts across the GTA, then browse Toronto lofts for sale to see how new pricing stacks up against recent resale.
This article is general information as of October 2026, not legal, tax, mortgage or financial advice. Rules and numbers change, so confirm the details for your situation with a licensed professional.