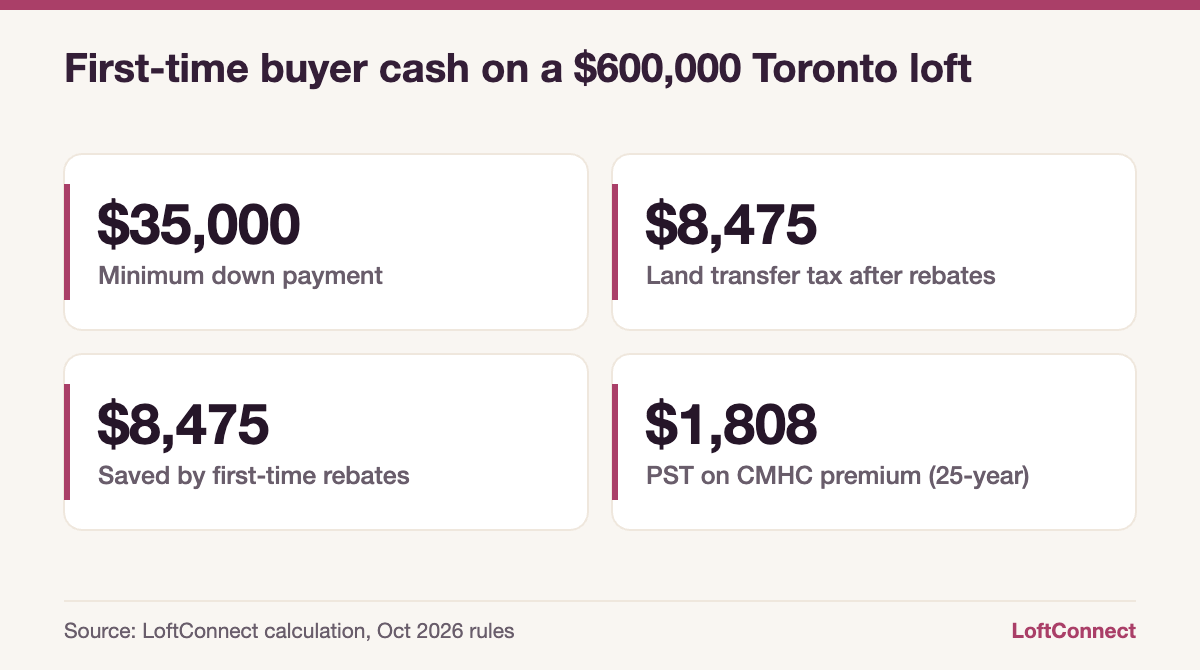
A first-time buyer purchasing a $600,000 loft in Toronto in 2026 needs at least $35,000 down, plus about $8,475 in land transfer tax after first-time rebates and $1,808 in sales tax on the mortgage insurance premium, before legal fees and adjustments. Without the rebates, the two land transfer taxes would total $16,950. FHSA and RRSP Home Buyers’ Plan withdrawals can cover much of the cash, and a 30-year insured amortization can lower the monthly payment.
Key takeaways
- Toronto buyers pay both Ontario and Toronto land transfer tax; first-time rebates cut up to $8,475 combined.
- The minimum down payment on a $600,000 loft is $35,000.
- The CMHC premium is added to your mortgage, but the 8% Ontario sales tax on it is due in cash at closing.
- First-time buyers can get a 30-year insured amortization through CMHC Home Start.
- The definitions of “first-time buyer” differ between programs, so check each one.
Land transfer tax on a Toronto loft
Buy anywhere in the City of Toronto and you pay two land transfer taxes: Ontario’s and Toronto’s municipal tax. Up to $2 million, the brackets are the same: 0.5% up to $55,000, 1.0% to $250,000, 1.5% to $400,000 and 2.0% above, under Ontario’s published brackets, which Toronto matches below $2 million.
| Loft price | Ontario LTT | Toronto MLTT | Total, no rebates | Total after first-time rebates |
|---|---|---|---|---|
| $500,000 | $6,475 | $6,475 | $12,950 | $4,475 |
| $600,000 | $8,475 | $8,475 | $16,950 | $8,475 |
| $750,000 | $11,475 | $11,475 | $22,950 | $14,475 |
The first-time buyer rebates
- Ontario: a refund of up to $4,000, which means no provincial tax on the first $368,000.
- Toronto: a rebate of up to $4,475, under the City’s MLTT rebate rules.
To qualify for the Ontario refund, you must be a Canadian citizen or permanent resident, must never have owned a home anywhere in the world (and neither can your spouse while they were your spouse), and must move in within nine months. You have 18 months to apply if the rebate isn’t claimed at registration. Toronto uses the same eligibility rules. Details are on Ontario’s refund page.
If you’d rather not pay Toronto’s tax at all, compare lofts in Hamilton or Mississauga, where only the provincial tax applies.
Down payment and CMHC insurance on a $600,000 loft
The minimum down payment is 5% of the first $500,000 and 10% of the rest: $25,000 plus $10,000, or $35,000. That leaves a $565,000 mortgage, about 94.2% of the price, which needs default insurance.
- 25-year amortization: premium of 4.00%, or $22,600, added to the loan. PST at 8% is $1,808, paid in cash at closing.
- 30-year Home Start amortization: premium of 4.20%, or $23,730. PST is $1,898.40.
At a 4.34% five-year fixed rate, the 25-year payment on $587,600 is about $3,200.15 a month. The 30-year payment on $588,730 is about $2,913.90, roughly $286 less, though you pay more interest over the life of the loan. Premium rates are from CMHC.
Qualifying: the stress test and condo fees
You qualify at the greater of your rate plus 2% or 5.25%, and insured mortgages cap housing costs at 39% of gross income (GDS) and total debts at 44% (TDS). Lenders count half your condo fee in GDS, which matters with lofts. Read why loft condo fees vary before you set your budget, and see what lenders look for in a loft mortgage.
Two definitions of “first-time buyer”
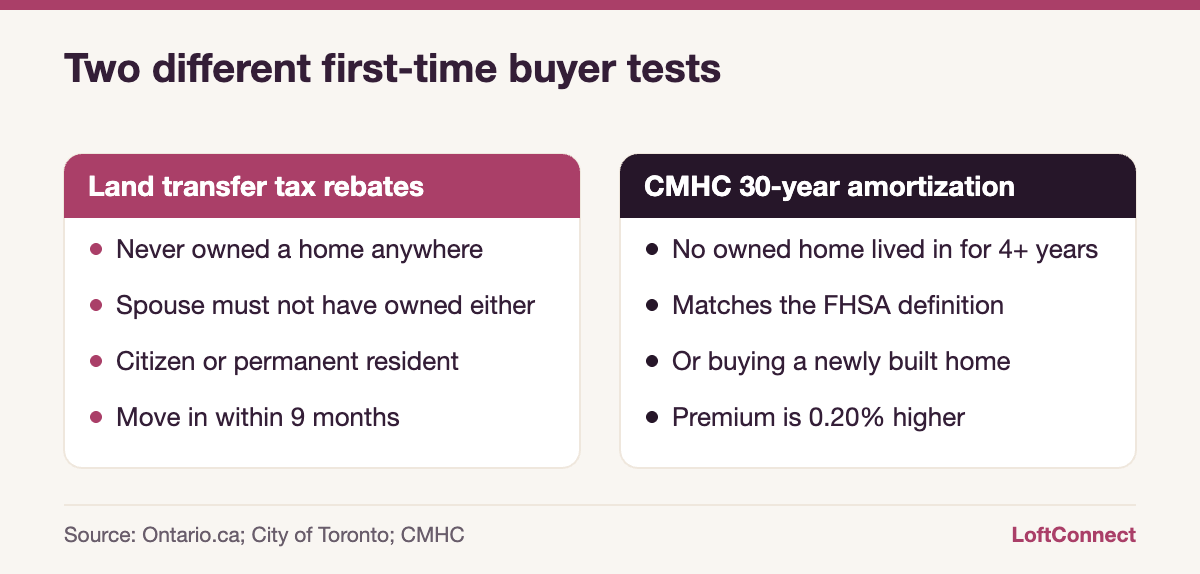
The 30-year insured amortization is open to buyers who haven’t owned and lived in a home in the current year or the four years before, the same test as the FHSA. The land transfer tax rebates require that you have never owned a home anywhere. If you owned a condo six years ago, you may qualify for a 30-year amortization and an FHSA, but not the land transfer tax rebates.
Using your FHSA and RRSP for a loft down payment
- FHSA: contribute up to $8,000 a year, to a $40,000 lifetime limit, with one year of unused room carrying forward. Contributions are deductible and qualifying withdrawals for a first home are tax-free.
- RRSP Home Buyers’ Plan: withdraw up to $60,000 and repay over 15 years. For first withdrawals made in 2022 to 2025, repayment starts in the fifth year after the withdrawal. The federal government has proposed extending that longer grace period to withdrawals through 2028; check the CRA’s Home Buyers’ Plan page for the rule in force when you withdraw.
A couple buying together can each use an FHSA and the HBP, which can cover the down payment and a good share of closing costs on a $600,000 loft.
A first-time loft buyer’s closing cost checklist
- Down payment: at least $35,000 on a $600,000 purchase.
- Ontario and Toronto land transfer tax, net of rebates.
- PST on the CMHC premium, due in cash.
- Legal fees, disbursements and title insurance: get two or three quotes.
- Status certificate review: the certificate itself costs no more than $100.
- Adjustments for prepaid property tax and condo fees.
- A home inspection if you want one; it’s optional but useful in older conversions.
- Moving costs, and a cushion for a low appraisal on a unique unit.
Tip: Many first-time buyers are drawn to large, older hard lofts at the same price as a small new unit. Before choosing, compare the monthly fee and the reserve fund, not just the square footage. A $300 higher fee can cost more over five years than the land transfer tax you saved with the rebates.
Buying a new soft loft instead?
New homes add HST, but first-time buyers may qualify for federal and Ontario relief, and since April 2026 an enhanced Ontario rebate is available to all eligible buyers. Our explainer on the HST rebate for new soft lofts walks through the numbers.
Frequently asked questions
How much do first-time buyers save on land transfer tax in Toronto?
Up to $8,475: $4,000 from Ontario and $4,475 from the City of Toronto. On a $600,000 loft, that cuts the combined tax from $16,950 to $8,475. To qualify you must never have owned a home anywhere, be a citizen or permanent resident, and move in within nine months.
What is the minimum down payment on a $600,000 loft?
$35,000. That’s 5% of the first $500,000 ($25,000) plus 10% of the remaining $100,000 ($10,000). You’ll need mortgage default insurance, and the premium is added to the loan, while the 8% Ontario sales tax on the premium is paid in cash at closing.
Can first-time buyers get a 30-year mortgage on a loft?
Yes, through an insured mortgage with CMHC Home Start, if you meet the first-time buyer test: no owned home you lived in during the current year or the previous four. The premium is 0.20 percentage points higher. On a $600,000 loft, it lowered the payment in our example by about $286 a month.
Can I use my FHSA and RRSP together to buy a loft?
Yes. You can withdraw from an FHSA and use the RRSP Home Buyers’ Plan for the same qualifying home, as long as you meet each program’s conditions. The FHSA lifetime limit is $40,000 and the HBP limit is $60,000 per person, so a couple can access significant down payment funds.
Ready to run your own numbers?
Try our loft buyer calculators, read the loft buyers’ guide, and browse Toronto lofts for sale in your price range.
This article is general information as of October 2026, not legal, tax, mortgage or financial advice. Rules and numbers change, so confirm the details for your situation with a licensed professional.
The newest lofts on the market
Fresh listings, updated every 15 minutes.
 $850,000211 - 625 Queen Street E, Toronto2+1 bed · 2 bath · South RiverdaleCourtesy of CHESTNUT PARK REAL ESTATE LIMITED
 $549,900624 - 200 Manitoba Street, Toronto1+1 bed · 2 bath · MimicoCourtesy of RE/MAX HALLMARK REALTY LTD.
 $729,900603 - 569 King Street E, Toronto1+1 bed · 1 bath · Moss ParkCourtesy of ROYAL LEPAGE REALTY PLUS
 $534,000216 - 8 Dovercourt Road, Toronto1 bed · 1 bath · Little PortugalCourtesy of SAGE REAL ESTATE LIMITED
 $824,900310 - 45 Dovercourt Road, Toronto1+1 bed · 1 bath · NiagaraCourtesy of CENTURY 21 PEOPLE`S CHOICE REALTY INC.
 $499,990528 - 65 East Liberty Street, Toronto1 bed · 1 bath · NiagaraCourtesy of HOMELIFE/MIRACLE REALTY LTD