When a loft appraisal comes in below the purchase price, the lender bases your mortgage on the lower figure, so the buyer has to cover the difference in cash, renegotiate, or rely on a financing condition to step away. Lofts are more prone to this than ordinary condos because there are fewer true comparables and their best features are hard to price. Both buyers and sellers can reduce the risk by preparing the appraiser with the right sales and documents.
Key takeaways
- Lenders lend on the lower of the purchase price and the appraised value.
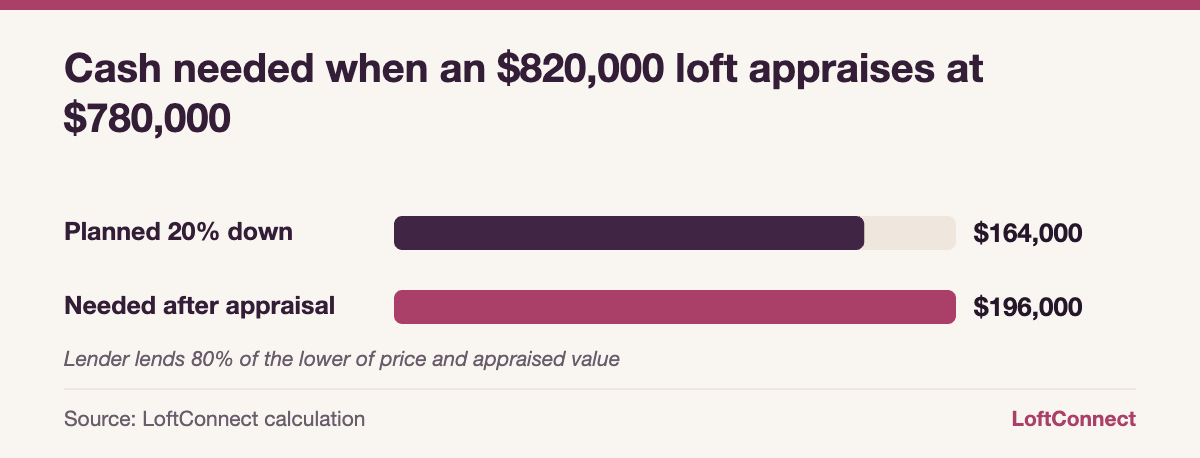
- On an $820,000 loft with 20% down, a $780,000 appraisal adds $32,000 to the cash you need.
- Unique layouts, mezzanines and few same-building sales make lofts harder to appraise.
- A financing condition is your protection; Ontario resale deals have no cooling-off period once firm.
- Giving the appraiser strong comparables and a measured floor plan helps both sides.
Why lofts appraise low more often
Residential appraisers mostly use the direct comparison approach: they find recent sales of similar units and adjust for differences. That works well in a tower with a dozen sales of the same floor plan. It works less well for a 1,100 sq ft corner hard loft with 15-foot ceilings and a private terrace in a 50-unit building.
Common reasons a loft comes in under the price:
- Few comparables. The appraiser falls back on soft lofts or standard condos, which don’t carry the same premium.
- Feature premiums are subjective. Original beams, brick, window walls and volume matter to buyers, but appraisers need sales evidence to support a dollar adjustment.
- Square footage disputes. A mezzanine may be counted in the listing but treated differently by the appraiser.
- A falling market. Comparables from six months ago may be above today’s level. The City of Toronto condo apartment benchmark was down 6.36% year over year in September 2026.
- Competitive bidding. If several buyers pushed the price up, the appraiser may not find sales to support it.
How a low appraisal creates a cash gap
Here’s the arithmetic on an $820,000 loft that appraises at $780,000, a $40,000 shortfall.
| Scenario | Planned down payment | Maximum loan on appraisal | Cash now needed | Extra cash |
|---|---|---|---|---|
| 20% down, uninsured | $164,000 | $624,000 (80% of $780,000) | $196,000 | $32,000 |
| 10% down, insured | $82,000 | $702,000 (90% of $780,000) | $118,000 | $36,000 |
Insured mortgages follow the same principle: the loan-to-value ratio, and the insurer’s limits under CMHC’s rules, are calculated on the lending value. Lofts priced at $1.5 million or more can’t be insured at all, which leaves even less room.
What buyers can do before the appraisal
- Keep a financing condition until the lender has the appraisal and final approval. Resale purchases in Ontario have no statutory cooling-off period, and a buyer who fails to close a firm deal risks losing the deposit and being sued for damages, as LegalLine explains.
- Ask your broker to pre-clear the unit with the lender, as covered in what lenders look for in a loft mortgage.
- Give your agent’s comparables to the broker so they can pass them to the appraiser, focusing on same-building and true hard loft sales.
- Keep a cash buffer on unique units. Bidding to the top of your budget leaves no room for a gap.
What buyers can do after a low appraisal
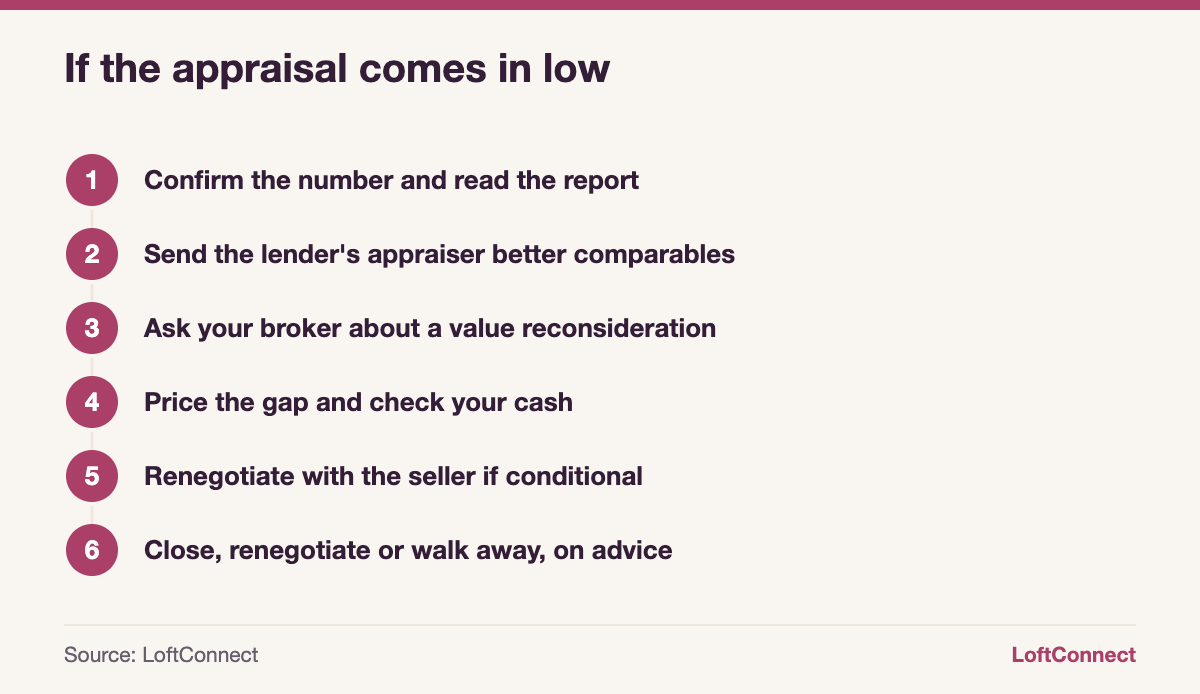
First, read the report. Check the square footage used, the comparables chosen and the adjustments. Errors happen, especially with mezzanines and parking.
Then consider your options:
- Ask for a reconsideration. Through your broker, send the lender additional comparable sales the appraiser may have missed. Lenders have their own processes and won’t always change the figure.
- Try another lender. A different lender may order its own appraisal. That takes time, so watch your condition deadline.
- Renegotiate. If you’re still conditional, you can ask the seller to reduce the price or split the difference.
- Cover the gap. If the loft is right and you have the cash, paying the difference may still be worth it.
- Walk away. Only if your condition allows it, and on your lawyer’s advice.
What sellers can do to help the appraisal
Sellers don’t order the appraisal, but they can make the appraiser’s job easier. Through your agent, provide:
- A list of recent same-building and nearby hard loft sales, with notes on why they compare.
- A professionally measured floor plan showing main floor and mezzanine separately.
- A feature sheet: ceiling heights, window sizes, parking, locker, outdoor space, recent upgrades.
- Receipts and approvals for renovations, including any registered alteration agreements.
Most importantly, price realistically from the start. Our guide on how to price a loft for sale walks through picking comparables. In September 2026, GTA homes sold for about 98% of list on average, according to TRREB, so a price well above recent sales is the most common cause of appraisal trouble.
If the buyer comes back asking for a reduction
Compare the appraisal’s comparables with your own. If the appraiser missed relevant sales, your agent can supply them. If the market has moved, a modest reduction to keep a qualified buyer may beat relisting, with more days on market and carrying costs. Start with our loft value estimate to sanity-check the number.
Tip: If your loft has a mezzanine, make sure the listing, the floor plan and the documents you send the appraiser all describe the square footage the same way. Mismatched numbers are one of the easiest ways for a loft to lose $30,000 on paper.
Frequently asked questions
What happens if a loft appraisal comes in lower than the offer?
The lender bases the mortgage on the lower appraised value, so the buyer needs more cash to close. If the deal is still conditional on financing, the buyer can renegotiate or, if the condition allows, walk away. If the deal is firm, the buyer is generally still obligated to close and must find the money.
Can I challenge a low appraisal?
You can ask, through your mortgage broker or lender, for a reconsideration supported by comparable sales the appraiser may have missed. The lender decides whether to revisit it. Another option is applying with a different lender, who may order a new appraisal, though timing against your condition deadline is tight.
Why do hard lofts appraise low?
Hard lofts often have few comparable sales, distinctive features that are hard to value, and square footage that can be measured differently with mezzanines. Appraisers need sales evidence for every adjustment. When the best comparables are soft lofts or standard condos, the appraised value can fall short of what a loft buyer will pay.
Does the seller have to lower the price if the appraisal is low?
No. A seller isn’t required to reduce the price. If the buyer’s financing condition is still open, the buyer can ask for a reduction or end the deal under the condition’s terms. Once the deal is firm, the buyer is generally bound to close at the agreed price regardless of the appraisal.
Planning to buy or sell a loft?
Check recent loft sold prices before you set a price or an offer, and read the sellers’ guide if you’re listing soon.
This article is general information as of October 2026, not legal, tax, mortgage or financial advice. Rules and numbers change, so confirm the details for your situation with a licensed professional.
The newest lofts on the market
Fresh listings, updated every 15 minutes.
 $850,000211 - 625 Queen Street E, Toronto2+1 bed · 2 bath · South RiverdaleCourtesy of CHESTNUT PARK REAL ESTATE LIMITED
 $549,900624 - 200 Manitoba Street, Toronto1+1 bed · 2 bath · MimicoCourtesy of RE/MAX HALLMARK REALTY LTD.
 $729,900603 - 569 King Street E, Toronto1+1 bed · 1 bath · Moss ParkCourtesy of ROYAL LEPAGE REALTY PLUS
 $534,000216 - 8 Dovercourt Road, Toronto1 bed · 1 bath · Little PortugalCourtesy of SAGE REAL ESTATE LIMITED
 $824,900310 - 45 Dovercourt Road, Toronto1+1 bed · 1 bath · NiagaraCourtesy of CENTURY 21 PEOPLE`S CHOICE REALTY INC.
 $499,990528 - 65 East Liberty Street, Toronto1 bed · 1 bath · NiagaraCourtesy of HOMELIFE/MIRACLE REALTY LTD