On Wednesday, October 28, the Bank of Canada raised its policy rate for the first time since July 2023, by a quarter point from 2.25% to 2.5%. A week earlier, a hold had looked likely. For loft buyers, the decision matters less than how you respond to it, so here is what the hike changes, what it does not, and the Toronto loft numbers behind both.
Updated: October 2026 — The Bank of Canada raised its policy rate to 2.5% on October 28, 2026. We first published this as a hike-or-hold preview and have rewritten it to reflect the decision.
The short version
- The hike happened: the policy rate rose from 2.25% to 2.5%, effective October 29, the first increase since July 2023.
- Prime is expected to rise from 4.45% to 4.70% as the big banks match the move.
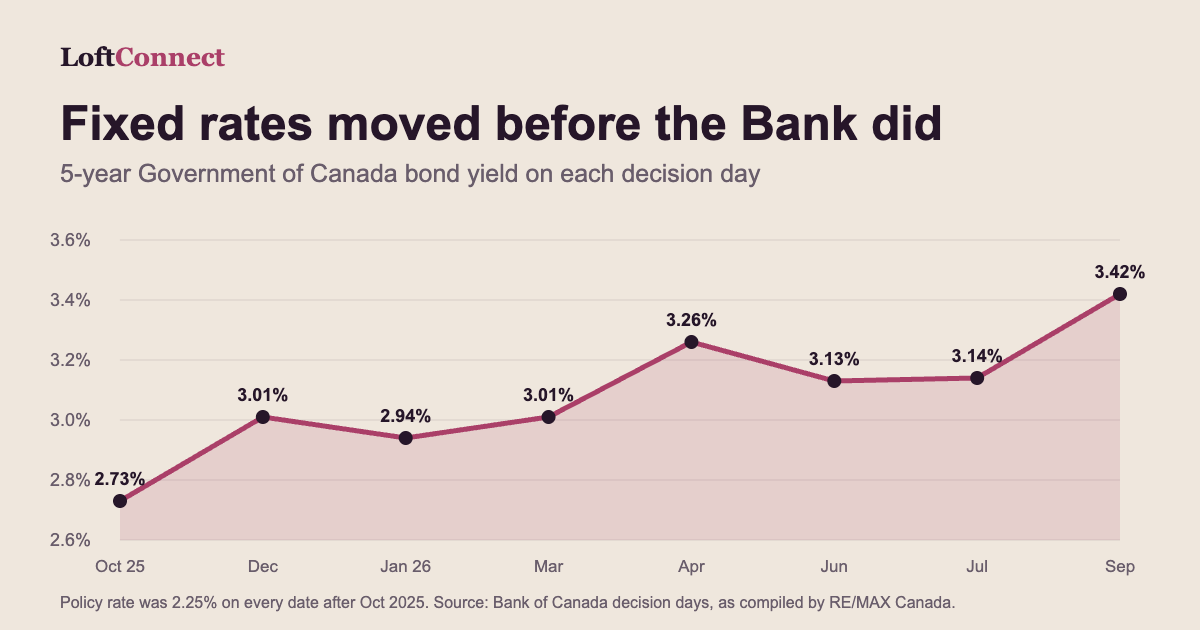
- Fixed rates had already moved. The 5-year bond yield rose from 2.73% to 3.42% across this year’s decision days while the policy rate sat still.
- The hike adds about $81 a month on a typical $600,000 variable loft mortgage.
- Toronto has 116 lofts listed against 81 sales in 90 days, about four months of supply.
- The move for buyers has not changed: rate hold first, then negotiate.
Why the Bank moved
When we published our October 28 primer for loft buyers, the market saw a hike as an outside chance. Then September inflation came in at 3.1%, driven by gasoline, and expectations swung within days. In its announcement, the Bank said it raised rates to reduce the risk that continuing high energy prices spread broadly to the prices of other goods and services. With the conflict in the Middle East in its eighth month, oil has stayed expensive, and the Bank now sees inflation rising to about 3.5% by the end of 2026 before coming back to 2% in mid-2028.
The counterweights have not gone away. The economy shed 68,000 jobs in September, unemployment is around 6.5%, inflation excluding gasoline was 2.2%, and the Bank expects housing to stay relatively weak. That is why its tone was careful: “There could be a need to increase the policy rate further, but given uncertainties, Governing Council agreed to proceed carefully.” The next decision is December 9, 2026.
What the hike changed, and what didn’t happen
What happened: a hike to 2.5%
- Prime is expected to move from 4.45% to 4.70% as the big banks match the move.
- Variable payments and HELOC costs rise once prime moves.
- The stress-test qualifying rate on a variable mortgage rises 0.25 points.
- Buyers at the top of their budget are likely to stay cautious.
- Another hike is possible, but the Bank says it will go carefully.
What didn’t happen: a hold at 2.25%
- Prime staying at 4.45% and variable payments staying flat.
- Sidelined buyers rushing back and firming up competition.
Notice what was never on either list: fixed mortgage rates falling back to where they were a year ago. Fixed rates follow bond yields, not the Bank’s decisions, and that is the part loft buyers tend to miss.
The loft math, before and after
Our October Toronto loft report puts the median asking price at $749,950 and the median monthly fee at $842. Here is what owning that loft costs with 20% down and a 25-year variable mortgage of about $600,000.
| Monthly cost | Before the hike (about 3.50%) | After the hike (about 3.75%) |
|---|---|---|
| Mortgage payment | $3,004 | $3,085 |
| Condo fee (median) | $842 | $842 |
| Total before tax and insurance | $3,846 | $3,927 |
The extra $81 a month is real money, but it is small next to price. On a $749,950 loft, negotiating 2% off saves $15,000 up front and trims the mortgage payment by roughly $60 a month on its own.
The fee line matters for qualifying, too. Lenders typically count a share of condo fees, often half, in your debt ratios. Hard lofts in older buildings can carry higher fees and trickier appraisals, which is why what lenders look for in a loft and what to do when a loft appraises low are worth reading before you offer.
Where the leverage is
Toronto had 116 lofts for sale this month and 81 sold in the last 90 days, roughly 27 a month. That is about four months of supply. Across the GTA, TRREB reported September sales down 9% year over year, and condo apartments took the longest of any home type to sell, at 42 days. In a market like that, sellers who need to move are more open to price, closing dates and conditions, especially on listings that have sat.
The split between loft types is worth watching. Hard lofts, the converted factories and warehouses, are asking a median of $924,000 this month, while soft lofts sit near $662,000. Larger balances feel rate moves more, so hard-loft buyers stand to gain the most negotiating room now that the hike is likely to keep the market cautious. Our guide to hard vs. soft lofts covers the trade-offs.
The move that has not changed: get a pre-approval with a rate hold, then shop. A hold commonly lasts 90 to 130 days and costs nothing, so you can take your time finding the right building without the rate moving under you, even if the Bank hikes again in December.
A loft buyer’s playbook for this week
- This week: ask your lender or broker for a rate hold, so the rate you qualify at is protected if prime or fixed rates move again.
- Run the budget as if the Bank hikes again, to a 2.75% policy rate, with our loft calculators. The Bank says a further increase could be needed, and its next decision is December 9.
- Get the fee and reserve fund picture early. A status certificate review protects you from surprise special assessments.
- Price your offer off solds, not asks. Check sold prices in the building.
- Selling and buying? Start with what your loft is worth and our guide on pricing a loft in a slower market.
Frequently asked questions
Did the Bank of Canada raise rates on October 28, 2026?
Yes. It raised its policy rate by a quarter point, from 2.25% to 2.5%, its first hike since July 2023. Prime is expected to rise from 4.45% to 4.70% as the big banks match the move. The next decision is December 9, 2026.
What happens to loft prices now that the Bank of Canada has raised rates?
No one can predict prices with certainty. What a hike usually does is keep some buyers on the sidelines. With 116 Toronto lofts listed and 81 sales in the last 90 days, the loft market already had about four months of supply going into the hike, which tends to give buyers room to negotiate.
Should I wait to buy a loft until rates settle?
Waiting does not guarantee a better rate. The Bank has said more hikes may be needed, and fixed rates follow bond yields rather than its decisions. A pre-approval with a rate hold protects your rate for up to about four months, so you can keep shopping without losing the rate you qualified at.
How much does the rate hike add to the cost of owning a Toronto loft?
On a $749,950 loft with 20% down and a variable rate moving from about 3.50% to 3.75%, the mortgage payment rises from about $3,004 to $3,085 a month. With a typical $842 monthly fee, total carrying cost goes from about $3,846 to $3,927.
Do condo fees affect how much mortgage I qualify for on a loft?
Yes. Lenders generally include a portion of the monthly condo fee, often half, in your debt ratios, so a loft with high fees reduces the mortgage you can qualify for. Higher rates make that effect bigger.
Find the loft before the market wakes up
Browse every loft for sale in Ontario, start with Toronto lofts, or get new loft listings by email the moment they hit the market.
General information as of October 28, 2026, not mortgage, legal or financial advice. Payment figures are estimates using illustrative rates; loft figures come from LoftConnect listing data for October 2026. Confirm your numbers with a licensed professional. Other sources: Bank of Canada (October 28, 2026 announcement and October Monetary Policy Report), Statistics Canada, TRREB, Reuters poll (October 21 to 23, 2026), LSEG.
The newest lofts on the market
Fresh listings, updated every 15 minutes.
 $850,000211 - 625 Queen Street E, Toronto2+1 bed · 2 bath · South RiverdaleCourtesy of CHESTNUT PARK REAL ESTATE LIMITED
 $549,900624 - 200 Manitoba Street, Toronto1+1 bed · 2 bath · MimicoCourtesy of RE/MAX HALLMARK REALTY LTD.
 $729,900603 - 569 King Street E, Toronto1+1 bed · 1 bath · Moss ParkCourtesy of ROYAL LEPAGE REALTY PLUS
 $534,000216 - 8 Dovercourt Road, Toronto1 bed · 1 bath · Little PortugalCourtesy of SAGE REAL ESTATE LIMITED
 $824,900310 - 45 Dovercourt Road, Toronto1+1 bed · 1 bath · NiagaraCourtesy of CENTURY 21 PEOPLE`S CHOICE REALTY INC.
 $499,990528 - 65 East Liberty Street, Toronto1 bed · 1 bath · NiagaraCourtesy of HOMELIFE/MIRACLE REALTY LTD